
NEW YORK — September inflation came in hotter than anyone wanted, and markets are paying for it.
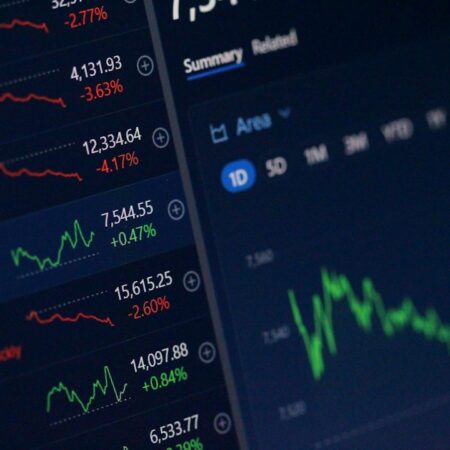
NEW YORK, October 14, 2026 — The S&P 500 traded near 7,727 at midday, down approximately 78 points or 1.1% from Tuesday’s close of 7,805, with the Nasdaq Composite off as much as 1.9% to 26,692, the Russell 2000 sliding 1.8% to 2,730, and the Dow Jones Industrial Average — insulated by its value-heavy composition — holding losses to around 0.25% near 51,560. The tape has three distinct wounds: a macro shock, a financial sector body blow, and a tech selloff that is starting to look structural rather than reactive.
The Macro Shock That Reset Expectations
At 8:30 AM ET, the Bureau of Labor Statistics released the September Consumer Price Index, and the number was unambiguous: headline CPI rose 0.6% month-over-month and 3.7% year-over-year, beating consensus of 0.4% and 3.6% respectively. Core CPI — the Fed’s preferred signal — held at 2.6% annually, one tick above the 2.5% forecast. This is the fastest pace of inflation since April 2026, and it dismantles the narrative that the disinflationary trend was intact.
The bond market responded before equities finished their open prints. The 10-year Treasury yield surged to 5.31%, up from 5.215% at Tuesday’s close, while the 2-year yield rose 12 basis points to 4.92%. That combination — a steep move at both ends of the curve — signals the market is repricing not just the next meeting but the terminal rate. The VIX climbed 8.9% to 16.63, still below levels that would indicate genuine panic, but the directional move is clear.
As we noted this morning in “Is 3.7% Inflation Enough to Revive Fed Tightening Fears?”, the setup was fragile. It was. The question now is whether one month of hot data is sufficient to drag the Fed back to the table — or whether Powell opts for a data-dependent pause and lets the bond market do the tightening for him. Gold, notably, offered no refuge: the metal dropped 1.8% to the $4,083 range, suggesting the dollar bid on rate expectations is overriding the traditional safe-haven trade.
Bank of America’s Double Trouble
Bank of America did not need a hot CPI day. The bank reported Q3 earnings per share of $0.91, well below the $1.09–$1.10 consensus, dragged down by a $1.21 billion regulatory penalty — $1.2 billion assessed by FinCEN for anti-money laundering violations, with additional charges from OFAC and the OCC — that reduced EPS by $0.17. Strip out the fine, and adjusted EPS of $1.08 actually beat the prior year’s $1.04. That nuance is cold comfort for a stock down 6–9% to the $49.34–$51.00 range at midday.
The underlying business tells a mixed story. Net interest income rose 8% to $16.4 billion, a genuine positive given the rate environment. Fixed income trading revenue, however, fell 17% to $2.55 billion — a sharp reversal that suggests the bond volatility that benefited traders in prior quarters is now generating client hesitation rather than volume. Equity trading rose 10% to $2.51 billion. Revenue came in at $30.0–$30.12 billion against a $30.55–$30.69 billion forecast.
This is the second consecutive session that bank earnings have disappointed on headline EPS. As covered in “Is the Hot CPI Print Finally Breaking Bank Stocks?”, the sector was already walking a fine line between rate-environment tailwinds and credit quality concerns. The BAC fine is a one-time event, but markets are not giving the stock the benefit of the doubt — and with the stock already down 11.93% over the past three months, there is no floor of investor goodwill to cushion the fall.
AI’s Credibility Problem Gets Louder
CoreWeave — the AI cloud infrastructure company that went public earlier this year — is the session’s most telling casualty. Shares fell as much as 15% to the $65.55–$68.04 range after the company announced a $3.0 billion convertible note offering due 2033 and an at-the-market equity program authorizing up to 35 million new shares. The dual capital raise, at a moment when CRWV’s bonds are reportedly trading to yield 15%, sent a clear signal: growth at this scale requires capital that is becoming increasingly expensive.
A Gartner warning that 80% of neocloud providers could lose competitiveness over the next two years added analytical weight to what might otherwise have been dismissed as a technical dilution trade. The RSI14 at 29.28 puts CRWV in oversold territory, meaning a technical bounce is plausible — but oversold can stay oversold when the fundamental narrative is deteriorating. Peer Nebius Group dropped 6–10%. The broader question, as explored in “Is the AI Trade Cracking Under the Weight of a 17% Chip Rout?”, is whether the AI infrastructure trade is entering a period of multiple compression regardless of individual company execution.
Dell’s 8–10% decline on the Barclays downgrade compounds the picture. Hardware vendors built their 2025–2026 bull case on AI server demand. That demand is real — but the gap between narrative and reported revenue is widening. When Barclays moves three names to Equal Weight in a single note, the signal is that the easy money in the trade has been made.
Sector Rotation and What the Breadth Data Reveals
Market breadth is the most alarming data point on the tape right now. With only 196 S&P 500 constituents advancing and 73.6% of all U.S. issues in decline, this is not a rotation — it is a broad liquidation. The Dow’s relative resilience, down just 0.25%, reflects the index’s tilt toward industrials, healthcare, and consumer staples names that carry less duration risk and less AI-premium valuation. That gap between the Dow and Nasdaq — roughly 1.4 percentage points of divergence — is the market expressing a clear preference for value over growth in a rising-rate environment.
The Russell 2000’s 1.8% decline is particularly instructive. Small caps are more sensitive to credit conditions than large caps, and a 10-year yield at 5.31% with a 2-year at 4.92% creates real financing pressure for smaller, more leveraged companies. The Russell is now trading near 2,730, approaching its 52-week low. A break below 2,725 would be a meaningful technical deterioration.
The Skydance Media (SKYD) decline of 22–25% is worth contextualizing: the drop follows the technical price adjustment tied to the Warner Bros. Discovery merger completion and the separate trading of 470.7 million warrants. This is a mechanical event, not a sentiment signal — though the headline number will generate noise.
Into the Close — The Levels That Matter
The afternoon setup is asymmetric. There are no scheduled Fed speakers today, which removes one potential catalyst for a reversal. The next hard data point that could shift the narrative is Thursday’s Producer Price Index release and weekly jobless claims. If PPI follows CPI higher, the Fed tightening narrative will be fully re-entrenched by end of week. After the close tonight, a handful of regional bank earnings and technology sector reports will test whether today’s selloff is sector-specific or the beginning of a broader Q3 earnings disappointment cycle. For a pre-market read on how the market positioned ahead of today, see “Will Today’s CPI Print Break the Market’s Fragile Calm?”
| Level / Event | Value | Signal |
|---|---|---|
| S&P 500 reclaim level | 7,780 | Failure to reclaim into close opens door for momentum shorts to extend overnight |
| 10-Year Treasury yield ceiling | 5.35% | A close above 5.35% resets equity risk premium models and hits growth valuations hardest |
| Russell 2000 support | 2,725 | Break below 52-week low territory; signals credit stress is spreading to small caps |
| CoreWeave (CRWV) RSI floor | 29.28 RSI | Technically oversold; watch for mean-reversion bounce attempt toward $70–$72 if volume fades |
| VIX escalation trigger | 18.00 | A move through 18 would signal systematic hedging is accelerating and could amplify late-day selling |
The afternoon is unlikely to deliver a clean reversal without a catalyst — and none is scheduled. The most probable scenario is a range-bound close between 7,720 and 7,760 on the S&P 500, with breadth remaining negative but volume tapering as institutions hold positions ahead of tomorrow’s PPI data. The more uncomfortable possibility — that 5.31% on the 10-year is not a ceiling but a waypoint — will not be resolved today. Position sizing into the close matters more than directional conviction.
This article is published by PreMarket Daily for informational purposes only. Nothing here constitutes financial advice, investment recommendations, or an offer to buy or sell any securities. Always consult a qualified financial professional before making investment decisions.
Other Articles
Inflation Bites Again — but Only Half the Market Is Listening
Is the Hot CPI Print Finally Breaking Bank Stocks?
No Comment! Be the first one.